A landscaping project can finish in profit and still be commercially disappointing.
If a job was expected to make £15,000 and finishes at £9,500, the important question is not whether it made money. It did. The question is when the business could have seen that the expected result was no longer realistic—and what it did at that point.
That is the difference between reporting job profit and controlling project margin.
A full order book tells you that customers want the work. A final project P&L tells you what the job ultimately made. Neither tells you, on its own, whether a manager had the information to protect the remaining margin, recover a legitimate change or alter the next quote before the same issue repeated.
Margin control is not an end-of-job report. It is a live commercial forecast.
The question is what the job will now make
A quote gives the business an expectation: project value, direct-cost assumptions and the profit the work is expected to deliver. That expectation should not disappear when the job is won.
As work progresses, the management question changes from “What have we spent?” to “Given what we know now, what is this job likely to make?” That requires more than costs already posted to an account. It requires a view of labour and material used, commitments still to come, work remaining, changes in scope and any issue that could alter the outcome.
This is not an argument for treating every live project view as a final account. It is not. It is a management forecast: a working assessment of whether delivery is still aligned with the commercial assumptions accepted at quote stage.
The practical discipline is to compare the original expectation with the likely outturn while the job is still under management. That means looking beyond cost recorded to date and considering known commitments, work remaining, agreed changes and the effect of the issue on the final result.
An overrun is not a diagnosis
A stage that is using more labour, materials or time than expected is not automatically a pricing failure. It is a prompt to investigate. The important part is identifying which commercial problem has actually emerged.
What management sees
The question that matters
The response it may require
Groundworks are taking longer than the allowance.
Has the site condition changed from the assumption priced?
Establish the effect on remaining work and determine whether scope, programme or a client decision needs to be revisited.
A retaining wall is within scope but has absorbed far more labour than expected.
Was the original allowance too light, or has delivery created avoidable exposure?
Improve the remaining delivery plan where possible and carry the evidence into the next comparable estimate.
Extra work has been completed after a client conversation.
Is the additional scope, cost, price and approval connected in one record?
Make the commercial position explicit before the project absorbs an unplanned cost.
At whole-job level, all three may simply appear as lower margin. They are not the same problem. One may require a client conversation; one may change the next estimate; one may require a different delivery decision on the live project.
That is why project sections or stages matter. They are not an administrative exercise. They are a way to locate the movement that needs management attention. The right structure will differ by project. On one job it may be groundworks, walling, paving and planting. On another, it may be phases, work packages or a recurring contract period. The objective is not a standard stage template; it is a practical way to understand where the commercial story changed.
Variations test whether commercial control is real
Most landscaping businesses understand that projects change. Clients ask for additional work. Site conditions alter the original approach. A design detail moves. None of that is unusual, and not every change is negative.
The exposure arises when production moves faster than the commercial record. The team carries out the work, but the changed scope, expected cost, client approval and billing position do not remain connected. By the time the cost appears in the final margin, the decision has effectively been made by default.
A robust project record should make four points clear:
What changed?
What is the cost and programme implication?
What has the client approved?
How does this affect the project’s expected outcome and billing position?
This does not mean every site conversation needs a complex form. It means a material change must be retrievable and commercially intelligible later. Accounting software should continue to hold the accounting transaction. The project record should explain the site event behind it. When those two views are disconnected, a business can see the cost without being able to judge whether it represents an original assumption, an authorised change or a delivery issue that should not be repeated.
A live review should end with a decision
The most useful review rhythm is not a generic weekly meeting. It is a short review triggered by the job’s own pace, uncertainty and commercial exposure. A fast-moving project may need attention at a key milestone; a longer project may justify a regular management check. The right rhythm is the one that allows action before the outcome is fixed.
The review should finish with a named decision, not just a variance figure. For each movement that needs attention, a manager should be able to say:
what has changed;
what it is now expected to mean for the completed job;
whether the cause is scope, estimating, delivery or a combination;
what happens next, who owns it and when it will be reviewed again.
There is no universal labour percentage, pound amount or reporting frequency that makes a variance material. A small movement may matter on a tightly priced project; a larger movement may be expected elsewhere. Each business should set the triggers that suit its work. What matters is that the trigger produces a timely management decision rather than a retrospective explanation.
The margin-control loop
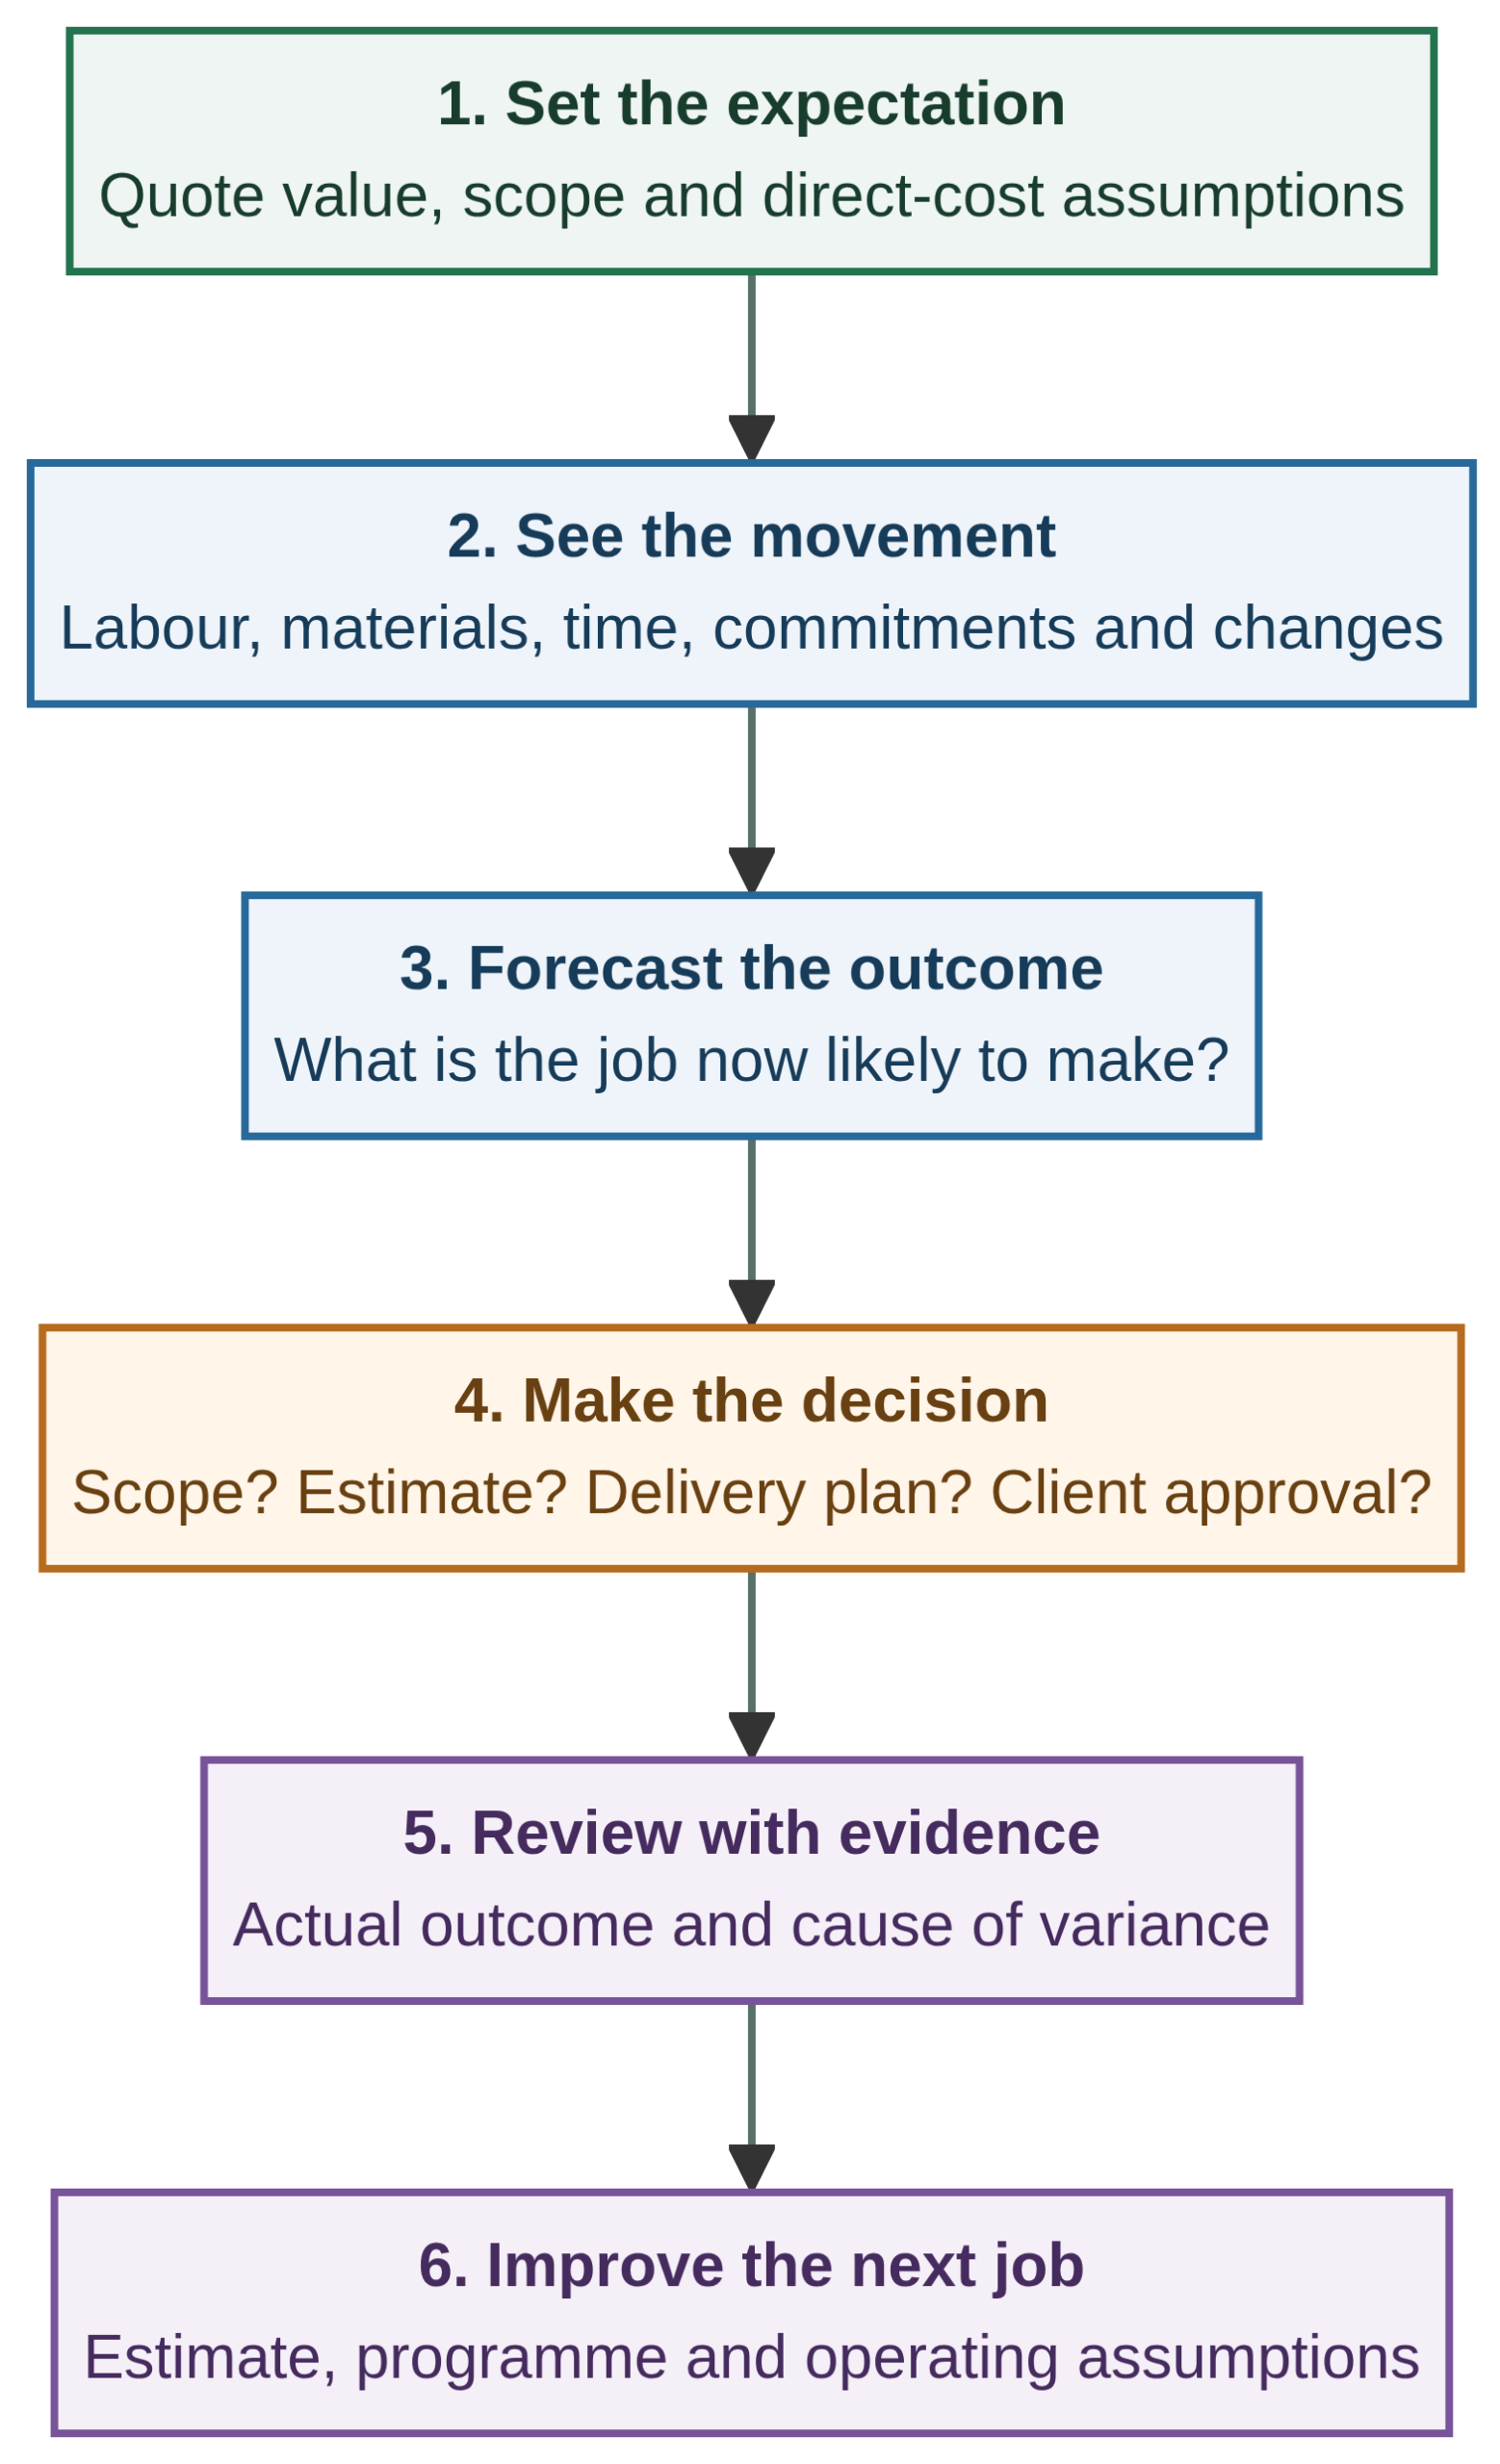
The discipline is straightforward, but the order matters:
Set the expectation. Carry a usable commercial baseline from the quote into the job. That may include labour, materials, plant, subcontractors and other direct-cost assumptions, structured in the way the business can genuinely review.
See the movement. Record delivery information against the project in sufficient detail to identify whether a stage, cost type or change is moving away from plan.
Forecast the outcome. Look beyond cost to date. Consider known commitments, remaining work and the expected effect of the issue on the final result.
Make the decision. Decide whether the business needs to act operationally, commercially or both. That might mean revising the delivery plan, clarifying a variation, changing a forecast or simply monitoring the issue.
Learn with evidence. When the project is complete, separate a difficult job from a repeatable commercial lesson. The next estimate, programme and site plan should be stronger because the business now knows what actually happened.
What a better review changes
A weak review concludes that a job was difficult. A useful review establishes why it was difficult and what that changes.
Perhaps the retaining-wall allowance was inadequate for a particular access condition. Perhaps a client-led change reached site before its commercial position was agreed. Perhaps the original programme did not account for a dependency that repeatedly delayed the crew. Those are different findings, and each should change a different decision.
CQ can support that discipline by linking the commercial expectation set at quote stage with project stages, delivery information, recorded time and cost, and the completed-project review. The principle comes first: a landscaping business should be able to see not only whether a job made money, but whether it delivered the margin it was expected to make, what changed and what that means for the next decision. To explore that approach across your own projects, see CQ’s landscaping business-management software or book a demonstration.
A completed project can always teach the next quote something. The stronger operating position is to learn while the job, the client conversation and the site context are still live.